

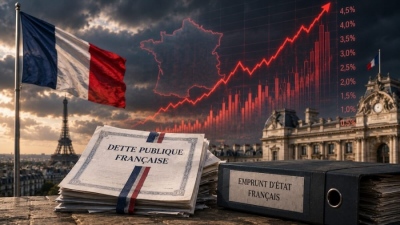
France accumulated debt of nearly 3.6 trillion euros, representing 119% of GDP at the end of June, according to data released on Tuesday by French statistical office Insee. The figures were made public as pessimism deepens over the future of the French economy, with debt levels now approaching those of Italy and Greece—two of the most indebted Eurozone nations—while economic growth remains stagnant. As a result of this situation, France's borrowing costs have surged.
Borrowing more expensively than Greece
On 10-year bonds, the yield has climbed to 4.73%, while the 30-year yield sits at 5.3%, marking the highest level since 2003. France is currently borrowing at higher rates than Greece, Italy, Spain, Portugal, and, naturally, Germany, whose 10-year bond yield stands at 3.65%. French Prime Minister Sébastien Lecornu stated earlier this month that he plans to propose budgetary savings totaling 54 billion euros in the 2027 budget, which is set to be officially presented on Thursday. Lecornu has pledged to cap the budget deficit—the difference between government spending and tax revenue each year—at 5% of GDP next year. However, it remains uncertain whether his government, which lacks a parliamentary majority, will manage to secure sufficient support for its proposed spending cuts and fiscal adjustment plans.
Deficit off target
France had set a target deficit of 5% of GDP for this year, but is likely to miss it due to sluggish growth and rising energy prices linked to the conflict in the Middle East. Even prior to Tuesday's data release, independent auditors and international organizations viewed France's commitment to lower its budget deficit below the European Union's 3% threshold by 2029 as unrealistic under current fiscal rules.
The 2027 budget in focus
The 2027 budget—the final budget to be debated by the government before next year's presidential election—has already sparked fierce pushback from Lecornu's left-wing opponents. At the same time, the nationalist National Rally, whose candidate Marine Le Pen leads in opinion polls, has delivered conflicting signals regarding its own plans for the budget and overall fiscal policy, Politico notes.
Political and social tension
France is entering a period of political and social tensions. Public sector workers were on strike today, with industrial actions hitting the transportation sector, healthcare, and education particularly hard, while it remains unclear whether a majority will emerge in the French National Assembly to pass the 2027 state budget. In the meantime, France has effectively entered a pre-election campaign season ahead of next spring's presidential race and the legislative elections that are widely expected to follow.
www.bankingnews.gr
Readers’ Comments